All Categories
Featured
Medicare Part D Enrollment and Drug Advice
Table of Contents
1 Investopedia - How Whole Life Insurance Coverage Works. 2 Thrivent Whole life insurance: Pros, cons & who it's right for. 3 Forbes - What Is Whole Life Insurance?
4 Forbes - What Is Variable Life Insurance? Material within this post is supplied for basic informational purposes and is not provided as tax, legal, health, or monetary advice for any individual or for any particular scenario.
For complete details, consisting of accessibility and expenses of Aflac insurance, please call your local Aflac agent/producer. Aflac life plans A68000 series/Term Life: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368200, ICC1368300, ICC1368400. In Delaware, Policies A68200, A68300 & A68400. In New York City, Policies NY68200, NY68300 and NY68400.
Indexed Universal Life Policies for Retirement
In Delaware, Policy A68100. In New York, Policy NYR68100. B60000/Term Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies ICC18B60200, ICC18B60300, & ICC18B60400. Not available in Delaware, Idaho, New York City and Oregon. Whole Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies: ICC18B60C10, ICC18B60100. Not readily available in Delaware, Idaho, New York City and Oregon.
In Delaware, Policy Q60200M. In New York, Policy: NYQ60200M. Whole Life: In Arkansas, Delaware & Oregon Policy Q60100M.
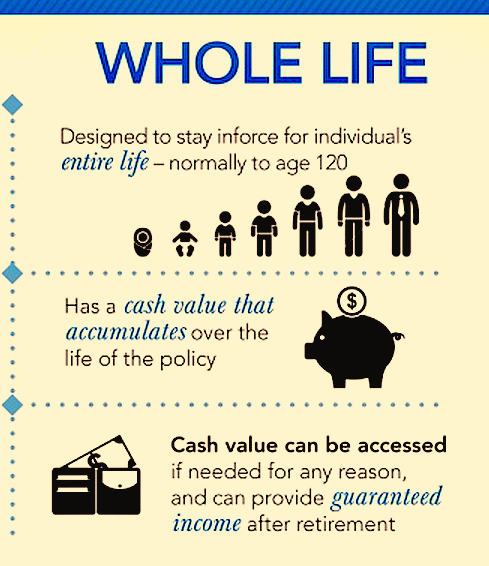
Coverage/plan levels might not be readily available in all states, including however not limited to NM or VT. Benefits/premium rates might differ based on plan chosen. Optional riders might be offered at an extra cost. Policies and riders may also include a waiting period. Refer to the exact policy and rider kinds for advantage details, meanings, limitations and exclusions. In this short article, we discuss what entire life insurance is and compare it to describe life insurance, along with universal life and variable life insurance. We likewise explain how entire life works and why many individuals prefer it over term. Before we jump into this subject, we have to answer one important concern: What is entire life insurance coverage? Put simply, it's a kind of insurance that ensures coverage for the life time of the guaranteed as long as premiums are being paid. Whole life insurance coverage likewise ensures the premiums and costs will never increase. Whole life insurance is one kind of permanent insurance coverage and is really different from term life insurance coverage, which provides protection for a specified period only and does not develop cash worth. This article explains how entire life insurance coverage works Lots of people think about life insurance coverage only in regards to a survivor benefit. Numerous of those functions, in some cases called living advantages, are extremely desirable, andthis is importantthose functions
The Mechanics of Whole Life Coverage
can not be discovered in any other kind of monetary product on earth. If term life insurance coverage is the most common form of life insurance, whole life insurance is the oldest kind of permanent life insurance coverage.(2 exceptions are suicide within the first two years, and pushing the insurance application.)On the other hand,"term policies are primarily created to last only for a limited period of time that will likely end before you die. "Having an insurance coverage that is guaranteed not to end before you do indicates that a policy you bought to supply protection for your household will secure them, anytime you pass away. You'll also get a totally free chapter from Pamela Yellen's New York Times best-selling book on this topic.] Whole life insurance coverage adds a component that term life insurance doesn't have. Part of your premium goes towards a savings portion of your policy. This is called the cash worth of your policy. This enables policies to be developed so that say goodbye to premiums are due once you retire, for example. You can get a loan at a rate that is often lower than banks offer.
Childrens Health and Dental CoverageThe bigger your money value, the bigger the loan you can take. You can use your cash worth to supplement your other retirement earnings. Entire life insurance coverage is the only kind of life insurance that guarantees of the following: The survivor benefit won't decrease The policy won't expire as long as premiums are paid Your premiums won't

go up Your costs will never ever increase The insurer guarantees that the money value of your whole life insurance policy will grow in time. figure out how much your cash value should grow based on existing interest rates, which, naturally, vary gradually. permit you to invest funds in policy subaccounts, comparable to shared funds. Your money value will increase orreduce, depending upon the performance of these subaccounts. What happens if performance of the cash worth of your universal or variable life policy drops? Who has to ante up more exceptional to keep your policy in force? You do. Neither option is great. If you have an entire life policy, you will not have to make those dreadful choices. The premium, cash value, and death advantage are all guaranteed. And did you understand you can discover precisely what your guaranteed premium, money worth and survivor benefit will be at any time before you decide if it makes sense to start a whole life policy? Just ask for a FREE, no-obligation Analysis here to take the first action. In such a way, it resembles getting an income tax refund. Now, dividends are not ensured. It's conceivable an insurer might have a dreadful, terrible, no great, extremely bad year . That's what the business prepares for. And every year that'smuch better than they prepared, they can pay a dividend. Get Your FREE Report! Get instantaneous access to the FREE 18-page Special Report that exposes how super-charged dividend paying entire life insurance lets you bypass Wall Street, fire your lender, and take control of your financial future. You get to inform the insurance company what to do with your dividend. and this just might be the neatest thing given that cupcakesyou can have them use your dividend to buy more insurance coverage for you insurance you'll never ever need to pay another premium for again. Think of that! You can purchase extra insurance coverage that's paid up, suggesting no more premiums will be due on that additionever. If that advises you of the eighth marvel of the worldcompound interestthat's due to the fact that the idea is precisely the very same. Just paid up entire life insurance additions build both your policy's cash value and your death benefit. You can learn more here about dividend-paying whole life insurance coverage, which many individuals find particularly amazing. Term life insurance premiums go upsometimes drasticallywith every brand-new term, because much of the cost of insurance is based on how most likely you are to pass away at a given age, and as you get older, that probability goes up. Universal and variable insurance premiums can go up, tooagain, in some cases drasticallyif money worth drops dueto low rate of interest or bad financial investment efficiency. So you may be asking, "If it costs more to guarantee my life with every passing year, how can a life insurance company assure my premiums will never ever go up?" The answer is elegantly simpleand it assists describe why whole life insurance is more costly than term insurance coverage in the early years of the policy.

Latest Posts

Locating Cheap Family Health Insurance
Selecting Best 2026 Medicare Advantage Plans
Signing up for 2026 Medicare Part D