All Categories
Featured

Affordable Life Insurance Strategies for Veteran Families
Table of Contents
With whole life insurance, you get to choose how your dividends will be utilized. Here are some of the choices: Purchase extra insurance, which can increase your survivor benefit and collected cash value quicker than your policy's initial warranties. When you use your dividend to acquire additional insurance coverage, it sets a new level of guarantee from which the policy's values can't fall from one year to the next Decrease the quantity of premium you owe each year.
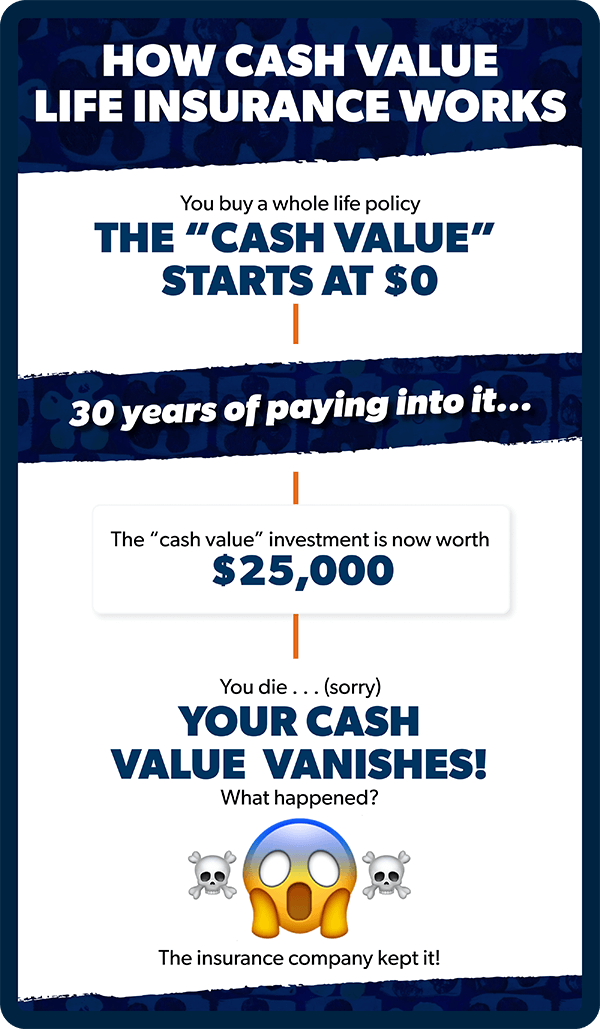
Your Northwestern Mutual monetary consultant can help you figure out the very best choice for you. Your policy will build up money worth that's ensured to grow with time and isn't tied to the stock marketmeaning it will not decrease after a drop in stock rates. And if you choose to utilize dividends to purchase extra insurance coverage, your accumulated money value and survivor benefit can increase even faster, intensifying gradually.
When accessing your cash worth, you have a couple of options to consider. You can take a loan against your policy from the insurance company. Payment of the loan is versatile, but interest will accrue. If you pass away with a loan versus the policy, your survivor benefit will be minimized by the amount of the loan.

Affordable Life Insurance Plans for Veteran Families
This might be an excellent choice if you have a financial emergency situation or for bigger, irregular needs, such as remodeling a home. When you surrender your policy, you'll no longer have your insurance coverage. Oftentimes, when individuals need to access their money value and no longer require their complete death advantage, they surrender a part of their policy.
This can likewise be helpful from a tax point of view. That's because when you give up a policy, you'll owe regular income tax on any cash value above money that you've paid in (or "basis"). In this case, you can take all the cash worth in your policy, however you likewise surrender all your life insurance coverage.
If you're considering using your money value, your financial consultant can help you analyze the very best alternatives for your scenario. If you have an optional waiver of premium rider on your policy, the company will pay your life insurance premiums if you end up being disabled. During this time, your cash value will continue to grow without you owing any cash for your policy.
Indexed Universal Life Benefits for Retirement
This advantage means that changes in your health will not impact your capability to get more insurance coverage down the roadway.
, particularly throughout down markets.
Otherwise, if you access those accounts while they are down, you 'd essentially be costing a loss.
How Whole Life Insurance Functions. Accessed March 26, 2026. Material within this post is provided for general informational functions and is not offered as tax, legal, health, or monetary suggestions for any person or for any particular situation.
Exploring How Whole Life Insurance Works
Aflac life plans A68000 series/Term Life: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368200, ICC1368300, ICC1368400. In Delaware, Policies A68200, A68300 & A68400. In New York City, Policies NY68200, NY68300 and NY68400. Whole Life: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368100. In Delaware, Policy A68100.
B60000/Term Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies ICC18B60200, ICC18B60300, & ICC18B60400. Whole Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies: ICC18B60C10, ICC18B60100.
In New York, Policy: NYQ60200M. Whole Life: In Arkansas, Delaware & Oregon Policy Q60100M. In Idaho, Policy Q60100MID.

Latest Posts

Securing Family Financial Security With Life Insurance

Finding the Optimal 2026 Medicare Supplement Plans
Affordable Life Insurance Strategies for Veteran Families